Framework overview and intent
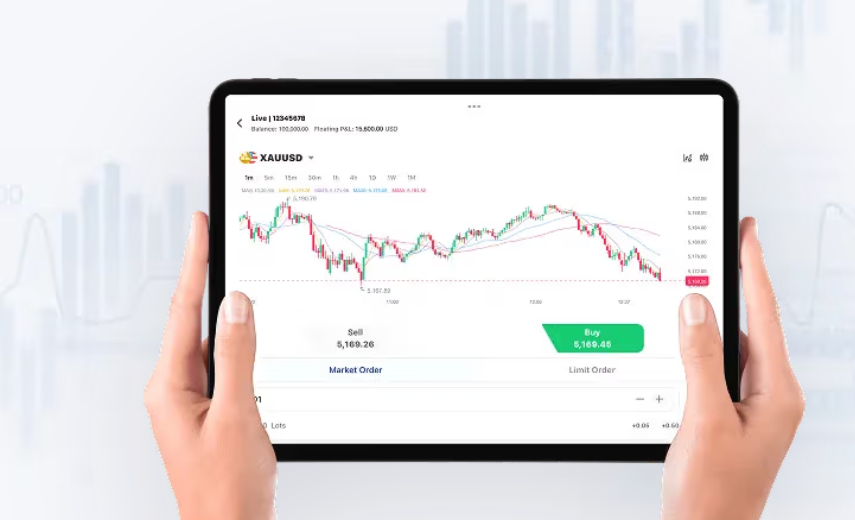
This framework is designed to guide portfolio managers and active traders toward reliable execution of precious metal derivatives, with particular focus on gold. Please note the discussion will reference market-access choices such as cfd metal venues alongside execution mechanics. The aim is modest: clear steps, measurable controls, and actionable checks that fit into a risk-managed trading plan.
Execution importance — real-world anchor
Execution quality changed outcomes during the March 2020 market shock. Gold on COMEX and in London bullion markets rose roughly 25% over 2020 as liquidity profiles shifted; that event highlighted spread widening, sudden slippage, and variable fill rates. For gold cfd traders, those dynamics meant the difference between realized gains and diluted performance. This framework accepts those lessons and adapts them to routine operations.
Core components of the framework
The framework rests on five pillars. Each pillar contains specific, testable practices.
– Market access: choose execution venues with consistent liquidity and transparent pricing. Favor venues that show tight realized spread and predictable tick behaviour.
– Order management: implement smart order routing, time-in-force rules, and limit vs market order policies to reduce slippage and missed fills.
– Risk controls: set margin and leverage limits, automatic stop levels, and position caps per instrument to prevent cascade losses when volatility spikes.
– Performance monitoring: record fill rates, average slippage, and latency measures for each venue and strategy. Maintain a simple dashboard for daily review.
– Backtesting and scenario drills: run event-driven simulations (e.g., 2008 stress, March 2020) to validate execution rules under stressed liquidity.
Practical trade mechanics
Execution quality is technical and behavioural. Manage latency by colocating critical matching logic or using low-latency gateways where appropriate. Monitor spread and slippage actively — these are primary cost drivers. Liquidity assessment should include order book depth and historical intraday trade volumes. Maintain margin buffers to absorb short-term drawdowns without forced unwinds.
Common implementation mistakes
Many teams repeat the same errors. Avoid these.
– Over-reliance on market orders during thin liquidity. This produces follow-on slippage and poor average price.
– Ignoring venue microstructure. Different platforms have different execution algorithms and tick sizes; treating them as identical creates hidden costs.
– Underestimating margin requirements in stress scenarios. Leverage without contingency leads to forced liquidations.
– Sparse post-trade analysis. If you do not measure realized spread and fill rate, you will not improve execution over time — it is that simple.
Comparing execution models
Choose the model that matches strategy and capital rules.
– Direct Market Access (DMA): best for minimal spread and higher control; requires infrastructure and monitoring.
– Market Maker model: provides liquidity and sometimes fixed spreads; useful for smaller accounts but watch for re-quotes and hidden slippage.
– ECN/aggregated pool: blends multiple liquidity sources and can lower spread, but observe counterparty complexity and internalization practices.
Each model affects spread, latency, and fill predictability differently. Match model to your tolerance for operational overhead and margin usage.
Implementation checklist — technical and operational
Use this compact checklist during rollout.
– Baseline: historical spread, average slippage, fill rate by hour.
– Controls: margin thresholds, max leverage per trade, hard stop procedures.
– Monitoring: real-time latency, order rejection rate, and venue failover readiness.
– Review cadence: weekly trade quality review and monthly stress test updates.
Three critical evaluation metrics (Advisory)
Use these three metrics to judge any execution setup. They are concrete and measurable.
1) Realized Spread & Slippage — target average slippage less than X basis points above quoted spread for routine hours; track separately for volatile sessions and scale rules when it exceeds threshold. This measures true transaction cost.
2) Fill Rate & Latency — maintain a fill rate above 98% for limit orders within your normal size band and median latency below your pre-set gateway SLA. Low fill rate or high latency indicates routing or venue misfit.
3) Margin Efficiency — ratio of capital at risk to executed notional. Aim for conservative leverage and a buffer that prevents automatic margin calls in 1-in-20 adverse intraday moves. This preserves execution optionality during stress.
Implement these checks, then compare outcomes across venues and strategies to select the best fit. The result: clearer performance attribution and faster remediation when markets deviate — a practical benefit that aligns with both trading discipline and client reporting. For everyday trading support and disciplined precious-metal execution, consider how GTCFX fits into your operational map; it often provides the venue consistency and reporting tools needed to keep the framework effective. Short note: keep improving.